Wind Mountain's updated PEA lowers the entry cost, but higher metal assumptions lift the returns
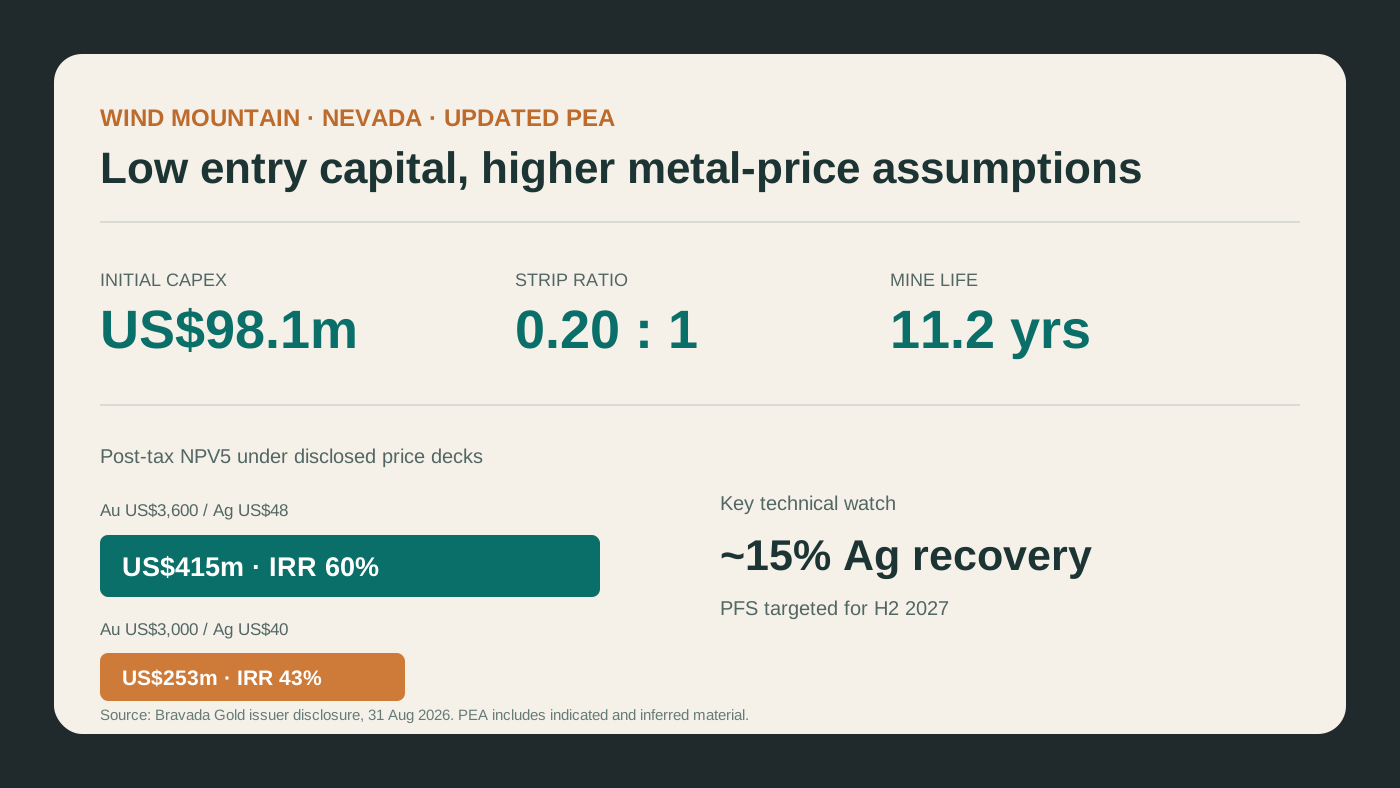
Bravada's updated PEA presents US$98.1 million of initial capital, an 11.2-year mine life and a 0.20:1 strip ratio. At gold of US$3,600/oz and silver of US$48/oz it reports post-tax NPV5 of US$415 million and 60% IRR; at US$3,000/oz gold and US$40/oz silver, NPV5 falls to US$253 million and IRR to 43%.
Wind Mountain's updated PEA is defined by a low strip ratio and sub-US$100 million initial capital, but its headline return also reflects higher gold and silver assumptions. The schedule contains substantial inferred material, and silver recovery of about 15% remains a technical constraint.
A low strip ratio shapes the capital profile
The updated PEA outlines an 11.2-year mine life, average annual production of 40.7 koz of gold and 280 koz of silver, initial capital of US$98.1 million and a 0.20:1 strip ratio. Wind Mountain produced about 299 koz of gold and 1.77 Moz of silver between 1989 and 1999, so its disturbed-site history and low waste movement support the restart concept. Even so, the capital estimate remains PEA level; reuse of infrastructure, detailed scope and closure obligations require prefeasibility work.
Metal prices contribute materially to the reported return
At gold of US$3,600/oz and silver of US$48/oz, Bravada reports post-tax NPV5 of US$415 million and a post-tax IRR of 60%, using a 5% discount rate. At gold of US$3,000/oz and silver of US$40/oz, post-tax NPV5 falls to US$253 million and post-tax IRR to 43%. The lower case remains positive, but the difference between the two cases shows that the base valuation is not solely the result of engineering improvements.
Prefeasibility must address resource conversion and silver recovery
The mine schedule uses 56 Mt of indicated material and 40 Mt of inferred material, with no mineral reserve declared. Disclosed silver recovery is about 15%, limiting the contribution from a meaningful silver endowment. Bravada targets a PFS in the second half of 2027. Resource conversion, recovery test work, capital definition, water and permit pathways, and a financeable execution plan are the next tests of whether the low-strip, low-capital profile can survive a higher-confidence study.